01Centralized AML for central banks
A connected view of financial crime risk.
Advisory, solution architecture and implementation for centralized AML platforms. Connect institutional reporting, shared data standards, supervisory dashboards and risk analysis within defined governance and access controls.
Centralized AML · Supervisory technology · Data integration
02AML technology & transaction monitoring
Turn activity into actionable intelligence.
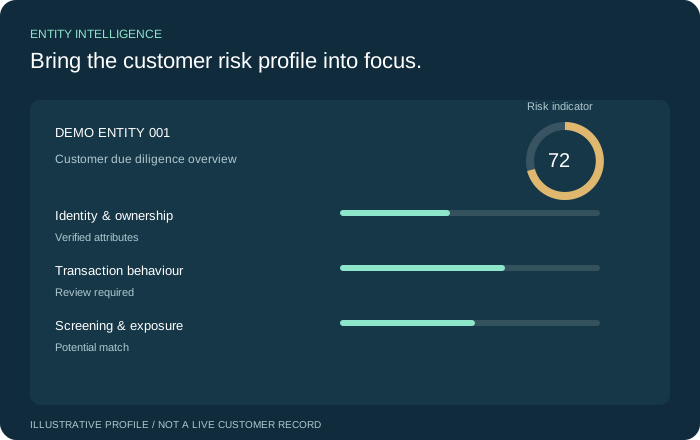
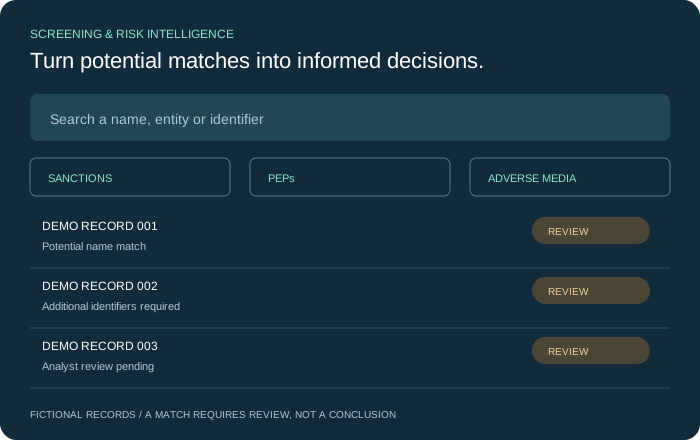
Design and integrate transaction monitoring, customer risk scoring, KYC/CDD and enhanced due diligence workflows, sanctions and PEP screening, alert management and investigation processes.
Transaction monitoring · KYC / CDD / EDD · Screening
03Fraud prevention & financial crime
Connect detection with investigation.
Fraud monitoring technology, detection scenarios and case workflows that help financial institutions identify suspicious patterns and coordinate response across channels.
Fraud detection · Scenario tuning · Case management
04AML/CFT advisory & remediation
From compliance gaps to stronger controls.
Assess the current environment, define a risk-based remediation roadmap, develop policies and governance, strengthen controls and prepare teams for implementation and ongoing review.
Gap assessment · AML/CFT frameworks · Remediation
05Compliance outsourcing
Specialist support for day-to-day operations.
Support for customer due diligence, screening reviews, alert investigation, documentation and compliance reporting preparation, with agreed service scope, escalation paths and institutional oversight.
Operational support · Quality assurance · Reporting
06Correspondent banking readiness
Build the foundations for banking relationships.
Strengthen due diligence documentation, compliance evidence and institutional readiness. Support engagement with prospective correspondent banks and responses to their onboarding requirements.
Due diligence · Relationship facilitation · Onboarding support
We support compliance remediation and correspondent banking engagement. Regulatory determinations and account-opening decisions remain with the relevant authorities and banks. Outsourcing scope is defined around applicable requirements and institutional oversight.